Home›Knowledge Center›Saudi Arabia

Saudi Real Estate Market Report 2026
Real Estate Market Reports · 2026 Edition

Saudi Real Estate Market Report 2026

Strategic analysis and market dynamics for 2026

Takamol Advanced's Saudi Real Estate Market Report 2026 offers a data-driven, institutional reading of the Kingdom's market across all thirteen regions, with a focus on Riyadh, Jeddah, Dammam/Khobar, Makkah, Madinah and the giga-project sites. Covering the reference period from Q3 2025 to Q1 2026, it is organised into nine themes that run from the macro economy and regulation through the residential, office, retail and hospitality sectors, and closes with ten ranked investment opportunities.

PDF · 66 pages · 15.0 MB

Key figures

$1.3T+

Announced construction and infrastructure project pipeline

4.1–4.9%

Non-oil GDP growth

830K

Housing units of confirmed demand by 2030

98–99%

Grade A office occupancy in Riyadh

540+

Global firms licensed for regional headquarters

150M

Visitors targeted by 2030

What the report covers

A summary of each theme. The full detail, charts and tables are in the report.

01

Executive Summary & Macro Landscape

Non-oil GDP is growing at 4.1–4.9%, fixed capital formation stands at 32% of GDP and the announced project pipeline exceeds $1.3 trillion, so property demand rests on deep capital restructuring rather than passing liquidity booms. The report puts confirmed cumulative housing demand to 2030 at 825–830 thousand units, while annual deliveries cover only 60–65% of organic demand. Institutional operating assets combine the highest yields with the lowest vacancy, such as serviced apartments at 8.0–9.2% and Riyadh Grade A offices at 8.2–8.8% net.
02

Offices & Regional Headquarters

Riyadh's office market is in a "Grade A squeeze": prime occupancy is 98–99%, rents in strategic locations are growing by more than 19%, and over 540 companies hold regional headquarters licences. Average Grade A rent in Riyadh is SAR 2,770/m² a year, reaching SAR 4,000 in KAFD against SAR 1,600 in Jeddah. The report expects about 1.1 million m² to arrive in 2027–2028 without a rental collapse, keeping prime net yields at 8.2–8.8%, while more than 70% of multinationals now require green certification.

03

Residential & Housing Market

Confirmed cumulative housing demand exceeds 830,000 units to 2030, with Saudi household ownership at 63.7% against a 70% target. Riyadh leads pricing, with apartments averaging SAR 5,150–5,400/m², 8.5% annual price growth and rents up 12–16%, compared with 2.5% growth in Jeddah and 1.8% in Dammam/Khobar. Apartments account for 62% of sales; 120–180 m² units priced at SAR 0.9–1.4 million sell more than 90% within the first months of launch, and Riyadh apartments return gross yields of 6.8–7.5%.

04

Retail & Lifestyle Centres

The report tracks a shift from enclosed malls to open lifestyle centres, as e-commerce grows by more than 20% a year and digital retail transactions in Riyadh rise by over 21%. Lifestyle and F&B centres run above 92% occupancy against an estimated 80% for traditional malls, and successful developers now give more than 50% of leasable area to dining and entertainment. Giga-projects add new destinations, including 900,000 m² of retail at New Murabba and an estimated 1.5 million m²+ of new retail and leisure space in Riyadh by 2030.

05

Giga-Projects & Logistics

Announced construction and development projects exceed $1.3 trillion, including more than $196 billion in contracts already awarded or under way and over 380,000 new homes within the giga-projects by 2030. Riyadh alone accounts for more than $314 billion of announced projects, and property near giga-project sites is recording price gains of 15–25%. In logistics, modern warehouse occupancy is close to 95% with rents rising 8–12% a year, while data centres deliver stable net yields of 8–9%.

06

Hospitality & Tourism

The Kingdom targets 150 million domestic and international visitors by 2030; RevPAR growth in Riyadh exceeds 18%, and the expected average daily rate for ultra-luxury products tops $1,200 a night. The west coast is adding more than 11,800 luxury keys in the first phase across the Red Sea and AMAALA, while Expo 2030 is generating demand for over 40,000 additional hotel rooms. The report's estimates show serviced apartments offering the fastest payback (5.5–7 years) and the highest IRR (16–19%).

07

Legislative & Regulatory Framework

The report charts regulatory decisions between Q3 2025 and Q1 2026 that moved the market from speculation to operational sustainability: non-Saudi ownership in designated zones, an expanded white land tax rising progressively to 10% in Riyadh with more than 411 million m² of undeveloped land identified, and the Tawazoun platform capping subsidised residential land at SAR 1,500/m². The Wafi off-plan system has also lifted off-plan projects by more than 60% in two years while cutting default risk to near zero.

08

Market & Transaction Data

Annual residential transaction values exceed SAR 50 billion despite fewer deals, and individual mortgage lending tops SAR 27.8 billion a quarter, confirming that genuine demand remains active despite high interest rates. Riyadh has a residential stock of 1.45 million units and 6.1 million m² of office space, less than 35% of it prime. Rental growth is led by Riyadh Grade A offices (up to 19%), followed by Riyadh housing (up to 16%) and warehouses (up to 12%), while Jeddah and the Eastern Province offer entry costs roughly 25–40% lower.

09

Takamol View: Opportunity Summary

The report closes with ten Saudi investment opportunities ranked by strength, led by build-to-rent serviced apartments for executives in north Riyadh yielding 8.0–9.2%, followed by pre-leased green Grade A offices in Riyadh and by modern warehouses and data centres with net yields of 8–9%. An investor matrix then maps the opportunities to investor profiles, from individuals with SAR 0.5–3 million and a 5.5–7.5% target yield to institutions and funds with more than SAR 300 million targeting 8–9%.

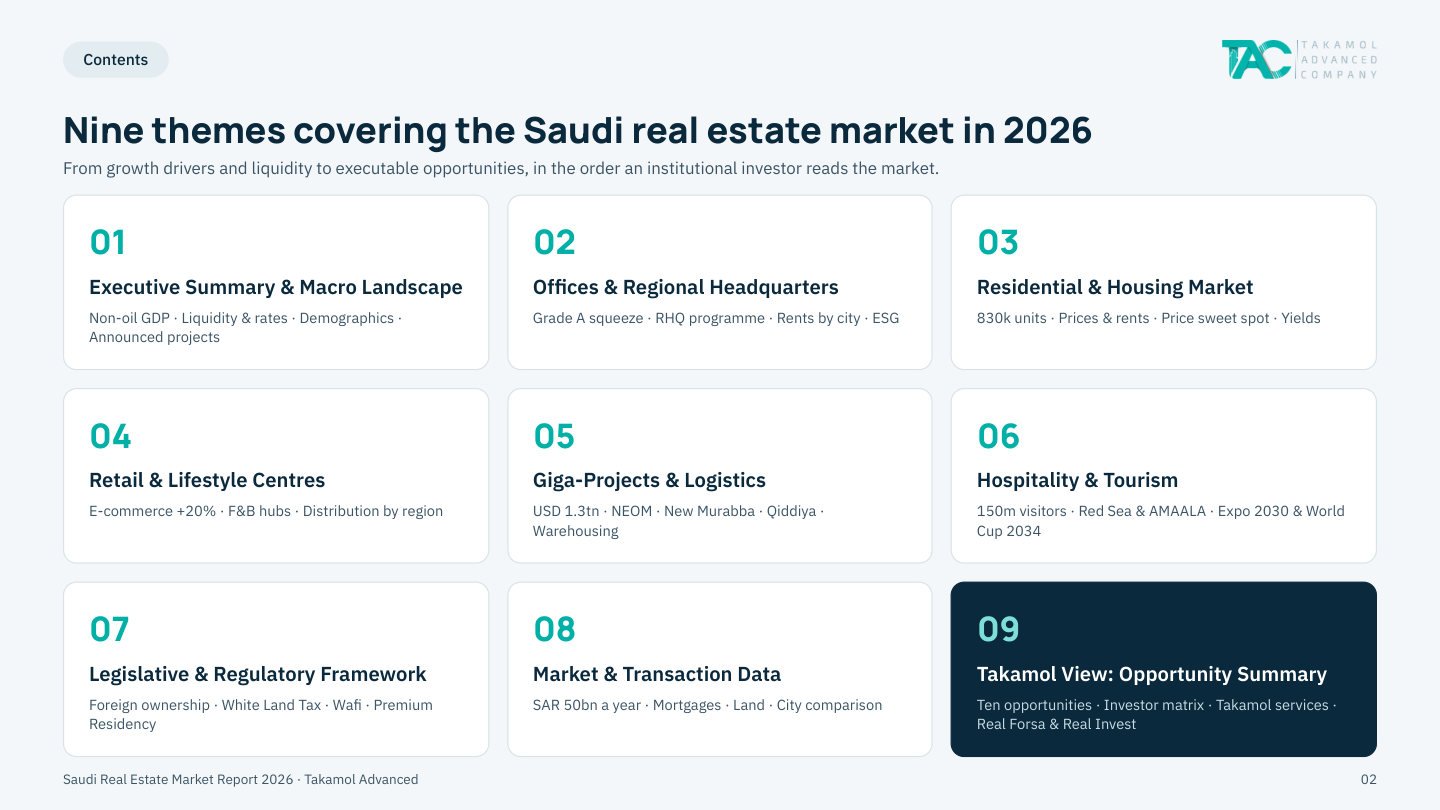
The report's contents page

Get the full report

The full report includes the detailed analysis, charts, data tables and their sources, along with the investment opportunity maps.

Download the PDF reportPDF · 66 pages · 15.0 MB

This summary is drawn from Takamol Advanced's 2026 real-estate market reports, and its figures are for general information. See the full report for detail and sources.

More reports