Home›Knowledge Center›Makkah

Real Estate Market Report — Makkah 2026
Real Estate Market Reports · 2026 Edition

Real Estate Market Report — Makkah 2026

Strategic analysis and market dynamics for 2026

This report offers an institutional reading of Makkah's real estate market across nine themes covering offices, housing, retail, Hajj and Umrah services and hospitality, alongside the regulatory framework, transaction data and opportunity maps. It covers the city and its four zones, with a reference period of January to August 2026, and concludes with ten investment opportunities ranked by strength for investors, developers and decision-makers.

PDF · 66 pages · 14.4 MB

Key figures

15.23M

Umrah performers in the Kingdom, Q1 2026

30M

Annual Umrah performers targeted by 2030

392K

Licensed hotel rooms in Makkah

34,000

Housing units planned for delivery, 2026–2028

443K m²

Retail gross leasable area in 2026

17.0–19.5%

Expected IRR for serviced apartments

What the report covers

A summary of each theme. The full detail, charts and tables are in the report.

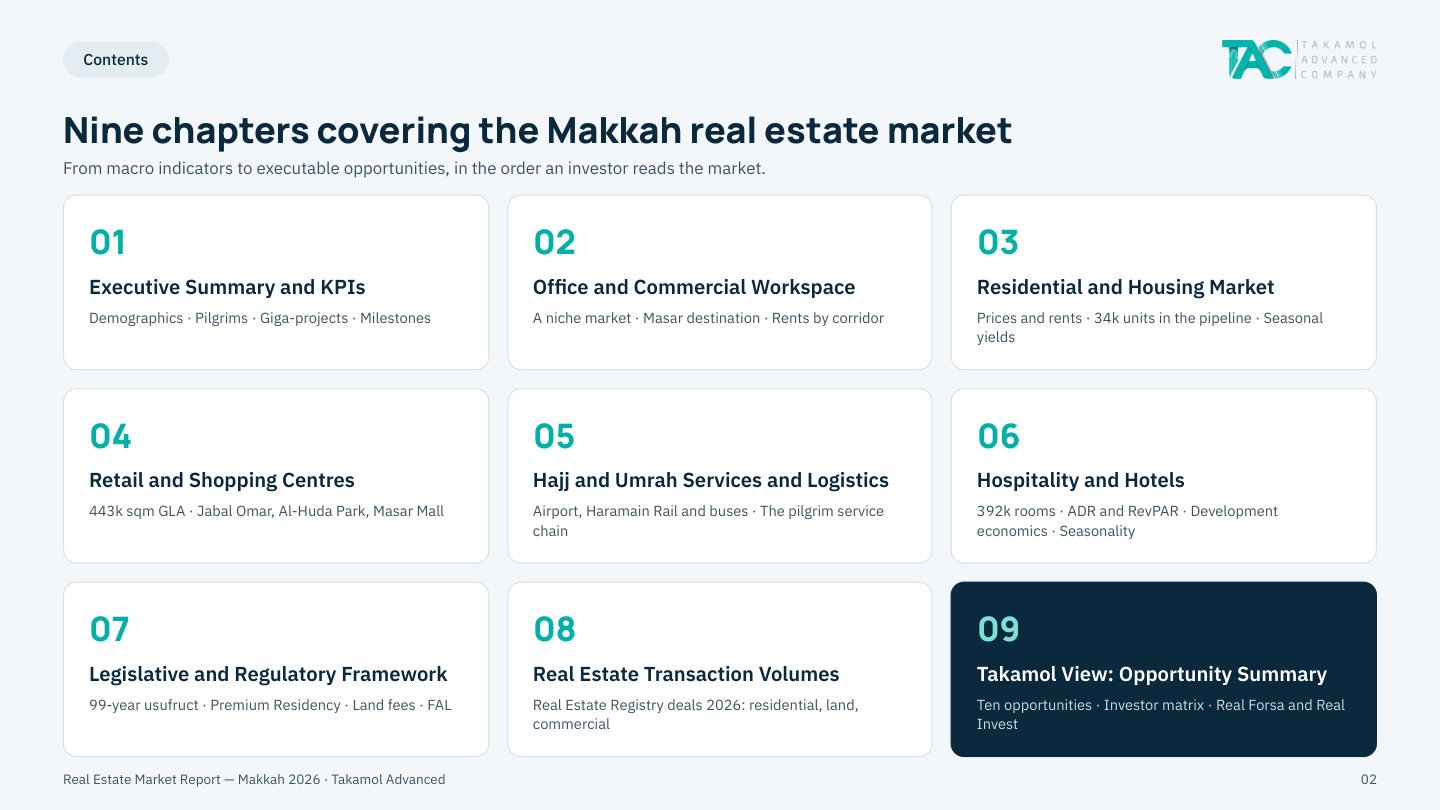
01

Executive Summary and KPIs

Makkah is the Kingdom's main hub for religious tourism: the region has 8.02 million residents, 2.43 million of them in the city, the 2025 Hajj season drew 1.673 million pilgrims, and the target is 30 million Umrah performers by 2030. The report estimates annual housing need at 15,000–20,000 units against roughly 11,300 delivered per year, an estimated annual gap of 3,700–8,700 units. Serviced apartments top the risk-return matrix with an expected IRR of 17.0–19.5%, followed by 4-star hotels at 15.5–17.8%.
02

Office and Commercial Workspace

A specialised office market, less mature than Riyadh and Jeddah, with an indicative range of SAR 500–900 per m² a year for modern offices and estimated occupancy of 98% for modern stock versus 75% for traditional buildings. Al Aziziyah and Al Masjid Al Haram Road lead rents at SAR 900 for Grade A (+3.5%), 1.9 times the level in Al Sharaei. The report expects new supply from Masar Destination in 2027–2028 to increase competition for traditional buildings while modern ones hold their position.

03

Residential and Housing Market

The existing housing stock exceeds 570,000 units, about 68% of them apartments. Apartment sale prices range from SAR 3,400 to 4,800 per m² (+3.2%), and apartment rents grew 6.2%. Around 34,000 units are planned for delivery in 2026–2028, led by the private sector (41%) and Makkah Gate and Wahat Makkah (36%). Net apartment yields are 6.4–7.4% on annual leases, rising to 8.5–10.5% with seasonal letting during the Hajj and Umrah seasons.

04

Retail and Shopping Centres

Retail gross leasable area stands at about 443,000 m² in 2026 and is expected to reach about 575,000 m² by 2028; upcoming projects include Al Huda Park and Masar Mall, which targets around 20 million visitors a year. Major centres record 98–99% occupancy against a market average of 86–87%. Rents near the Haram (about SAR 10,800 per m² a year) are roughly five times those of neighbourhood centres (about SAR 2,100), and pilgrims and Umrah performers account for 45% of retail demand.

05

Hajj and Umrah Services and Logistics

Makkah's access system carries the largest flow of people in the Kingdom: 53.4 million passengers through King Abdulaziz International Airport in 2025, 15.23 million Umrah performers in Q1 2026 (5.77 million from abroad), and a bus network of more than 580 km with 431 stations. The report treats logistics as a real estate sector in its own right: more than 392,000 rooms need central kitchens, catering warehouses and laundry and maintenance facilities, and it identifies 2,000–5,000 m² chilled kitchen and warehouse units as the clearest gap in the market.

06

Hospitality and Hotels

Supply exceeds 392,314 licensed rooms (+5.4%), with average annual occupancy of 59.9% that jumps to 98–100% in the central area during the last ten nights of Ramadan and the Hajj season. Average daily rate reached SAR 780 (+11.5%) and RevPAR SAR 510 (+15.2%), with gross operating profit margins of 46–52%. Serviced apartments offer the strongest economics, with an IRR of 17.0–19.5% and a 5.2–6.5-year payback, while the ADR gap between the Haram area and the Kudai zone exceeds 16 times.

07

Legislative and Regulatory Framework

A special framework for Makkah grants non-Saudis renewable usufruct rights of up to 99 years in major developments such as Masar Destination, Thakher Makkah and Jabal Omar, with a SAR 4 million minimum asset value for “Real Estate Owner” premium residency holders. Transaction costs total about 7.5% (5% transaction tax plus brokerage capped at 2.5%). White land fees have been invoiced on more than 28 million m², of which over 12 million m² has entered development or trading, leaving about 16 million m² as a pool for development partnerships.

08

Real Estate Transaction Volumes

The real estate registry recorded about 2,200 transactions worth roughly SAR 3.8 billion in Q2 2026, an average of about SAR 1.73 million per deal, while the average apartment price was about SAR 3,437 per m² in Q1. Land leads activity outside the centre, with 2,942 vacant land transactions worth SAR 2.22 billion at an average of about SAR 1,270 per m². Commercial deals are fewer but larger, with the highest recorded transaction reaching SAR 256 million in the Al Diyafah district.

09

Takamol View: Opportunity Summary

The report closes with ten investment opportunities ranked by strength, led by usufruct-based serviced hotel apartments in Masar Destination and around the Haram (IRR 17–19.5%), followed by 4-star hotels on the Masar axis and near shuttle transport stations, and flexible ownership apartments with pilgrim housing permits. An investor matrix matches each opportunity to a profile, from individual investors with SAR 0.5–3 million and a target return of 6.4–10.5% to institutions and funds with more than SAR 300 million.

The report's contents page

Get the full report

The full report includes the detailed analysis, charts, data tables and their sources, along with the investment opportunity maps.

Download the PDF reportPDF · 66 pages · 14.4 MB

This summary is drawn from Takamol Advanced's 2026 real-estate market reports, and its figures are for general information. See the full report for detail and sources.

More reports