Home›Knowledge Center›Eastern Province

Real Estate Market Report — Eastern Province 2026
Real Estate Market Reports · 2026 Edition

Real Estate Market Report — Eastern Province 2026

Strategic analysis and market dynamics for 2026

The Eastern Province Real Estate Market Report 2026 offers an institutional reading of the office, residential, retail, industrial, energy, logistics and hospitality sectors, together with the regulatory framework, transaction data and opportunity maps, for investors, developers and decision-makers. It covers the province and its governorates, with a focus on the Dammam metropolitan area (Dammam, Khobar and Dhahran), Qatif, Jubail, Al-Ahsa and Hafr Al-Batin, over a reference period of January to August 2026.

PDF · 66 pages · 16.3 MB

Key figures

5.13M

Residents of the Eastern Province

SAR 366bn

FDI stock, 42% of the Kingdom's total

34

Global companies licensed for regional headquarters

2,626

Producing factories, 25.3% of the Kingdom's

8.1M+ sq m

Logistics space, the largest in the Kingdom

90%+

Industrial and logistics occupancy, Dammam metro

What the report covers

A summary of each theme. The full detail, charts and tables are in the report.

01

Executive Summary & KPIs

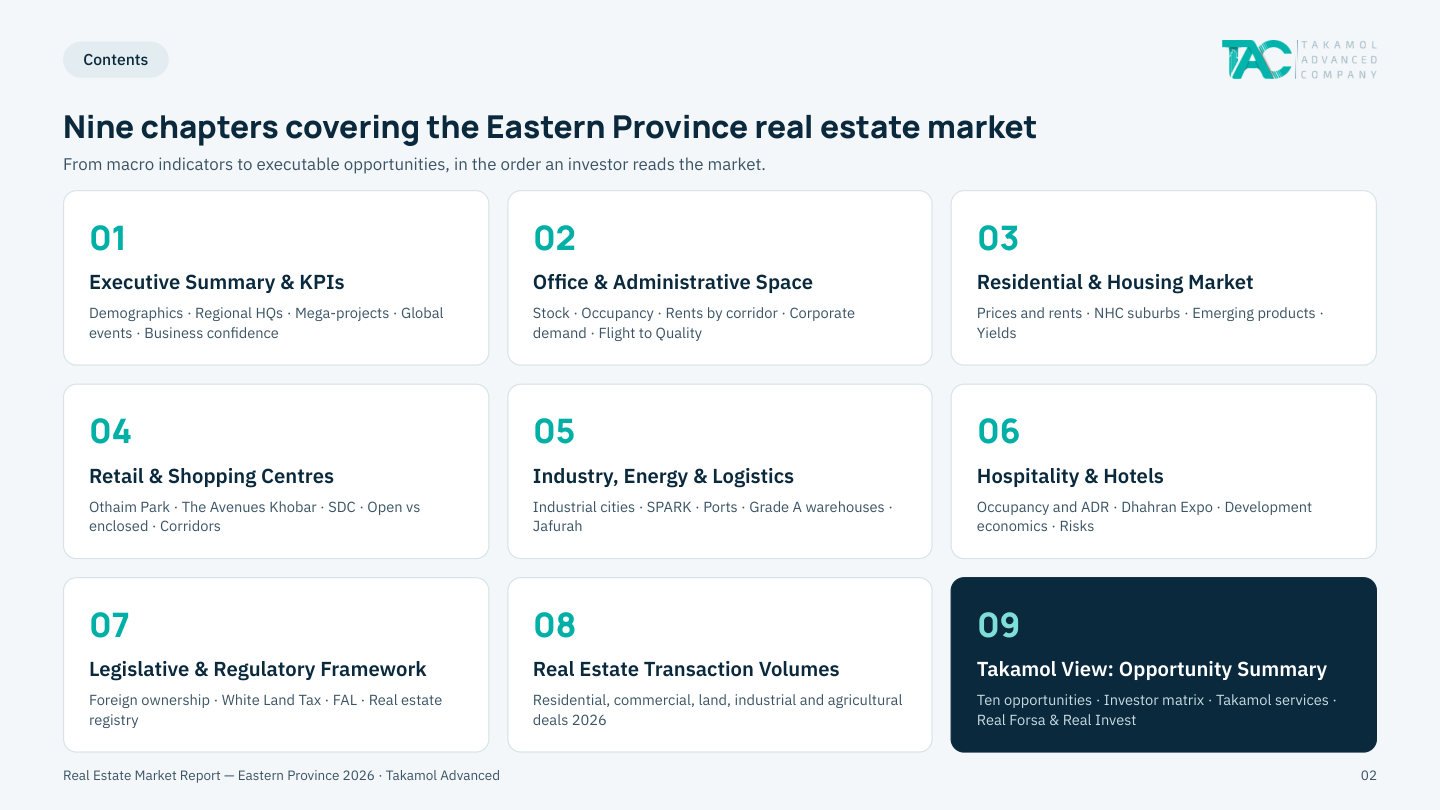
The report presents the Eastern Province as the Kingdom's centre of gravity for industry, energy and logistics, with 5.13 million residents, 5.0% annual population growth (the highest among major regions) and average household income of SAR 15,000 a month. FDI stock is about SAR 366 billion (42% of the Kingdom), and 34 global companies have chosen to open regional headquarters here. Annual housing need of 20,000 to 24,000 units compares with about 9,700 planned deliveries a year, an estimated annual gap of 10,000 to 14,000 units.
02

Office & Administrative Space

The Dammam metro area has about 2.04 million sq m of lettable office space, with Grade A occupancy at 78.6% (JLL) against about 91% for prime assets (CBRE). Grade A rents rose 9.2% to about SAR 994 per sq m a year, versus SAR 840 for Grade B; a gap of only 18% makes upgrading easy for tenants, the essence of the flight to quality. The Khobar waterfront leads at up to SAR 1,035. With about 129,640 sq m arriving in 2026, the report expects rental growth to slow and older buildings to see higher vacancy.

03

Residential & Housing Market

Housing stock totals 1,349,769 units, about 745,000 in the Dammam metro area and 240,000 in Al-Ahsa. Apartments sell for SAR 3,300 to 4,450 per sq m (up 0.8%) and villas for SAR 4,200 to 5,600 (up 1.4%), even as transactions fell 14.2% in Q1 2026, which the report reads as selectivity, not weakness. About 29,000 units are due in 2026–2028, 71% from National Housing Company projects, and an illustrative model shows a 7.8% gross yield for a Khobar apartment against 5.3% for an Al-Ahsa villa.

04

Retail & Shopping Centres

Retail GLA in Greater Dammam reached about 1.42 million sq m in H1 2026, with 94% occupancy at major destinations and 95% at open-air centres such as Ajdan Walk, while regional-mall rents averaged SAR 2,198 per sq m a year, down 1.5%. More than 458,000 sq m arrives by 2028 through Al Othaim Park, The Avenues Khobar, SDC Khobar and Al Othaim Circle, about a third of existing stock and the largest retail supply wave the province has seen. Khobar–Dhahran rents are about 1.7 times those in Al-Ahsa.

05

Industry, Energy & Logistics

The province hosts 2,626 producing factories (25.3% of the Kingdom's), over 40 million sq m of developed industrial land and over 8.1 million sq m of logistics space, the Kingdom's largest. Industrial and logistics occupancy in the Dammam metro area exceeded 90% in Q2 2026 amid a Grade A shortage, with modern warehouses estimated at about SAR 260 per sq m against about SAR 150 for traditional stock. The sector targets net yields of 8.5% to 9.5%, driven by King Abdulaziz Port (3.23 million containers in 2024), SPARK and the Jafurah gas field.

06

Hospitality & Hotels

Licensed hotel supply is about 16,234 keys (up 4.8%), with annual occupancy of 58.4% rising to 82–90% in Khobar and Dammam during holidays and seasons, and an average daily rate of SAR 465. Serviced apartments lead the development economics, with an expected IRR of 16.0% to 18.5% and a 5.5 to 6.8-year payback, backed by demand from energy and project staff. Khobar Corniche daily rates run up to 3.7 times Jubail's, and Tourism Development Fund packages cover up to 60% of capital costs for Khobar beach resorts and Al-Ahsa heritage hotels.

07

Legislative & Regulatory Framework

Non-Saudis can own 100% in the SPARK and Ras Al-Khair special economic zones and in approved zones on the Khobar and Dammam waterfronts and Dhahran's office towers. Transaction costs total about 7.5% (5% transaction tax plus brokerage capped at 2.5%), and first homes are exempt up to SAR 1 million. White-land fees reach 10% of land value a year; more than 95 million sq m has been invoiced and over 19 million sq m in the Dammam metro area has entered development or changed hands, opening partnership opportunities with landowners.

08

Real Estate Transaction Volumes

The residential sector recorded 7,772 transactions in 2026 worth SAR 6.95 billion, about 15.7% of the Kingdom's deals, averaging SAR 894,000. Khobar takes 37% of residential value with only 14% of deals, at SAR 3,549 per sq m, the province's highest. The commercial sector logged 956 deals worth SAR 3.52 billion, averaging SAR 3.68 million, with value up 27.1% year on year. The section also covers vacant land, industry and agriculture, including 150 agricultural deals worth SAR 175.4 million.

09

Takamol View: Opportunity Summary

The report closes with ten investment opportunities ranked by strength, led by Grade A warehouses near King Abdulaziz Port and the Second Industrial City (occupancy above 90%, net yields of 8.5% to 9.5%), then serviced apartments for energy staff in Dhahran and Jubail (IRR of 16% to 18.5%) and build-to-rent housing for oil, gas and port companies (7% to 8% yield). An investor matrix matches each to capital and horizon, from individuals (SAR 0.5 to 3 million, targeting 5.5% to 7.5%) to institutional funds (over SAR 300 million, targeting 7.5% to 9.5%).

The report's contents page

Get the full report

The full report includes the detailed analysis, charts, data tables and their sources, along with the investment opportunity maps.

Download the PDF reportPDF · 66 pages · 16.3 MB

This summary is drawn from Takamol Advanced's 2026 real-estate market reports, and its figures are for general information. See the full report for detail and sources.

More reports