Home›Knowledge Center›Al-Qassim

Real Estate Market Report — Al-Qassim 2026
Real Estate Market Reports · 2026 Edition

Real Estate Market Report — Al-Qassim 2026

Strategic analysis and market dynamics for 2026

Takamol Advanced's 2026 report on the Al-Qassim real estate market offers an institutional reading of the office, residential, retail, industrial and logistics, and hospitality sectors, together with the regulatory framework, transaction data and opportunity maps, for investors, developers and decision-makers. It covers the region and its 13 governorates, with a focus on Buraidah, Unaizah, Ar Rass, Al Bukayriyah, Al Badai and Al Mithnab, over a reference period of January to August 2026, and closes with ten investment opportunities ranked by strength.

PDF · 66 pages · 15.9 MB

Key figures

1.34 million

Residents of the Al-Qassim region

730

Producing factories, 4.7% of the Kingdom's total

14,282

Residential deals worth SAR 5.03 billion

96%

Occupancy at Buraidah's First Industrial City

8.5–9.2%

Target net yield, logistics and cold storage

8,500

Housing units due for delivery 2026–2028

What the report covers

A summary of each theme. The full detail, charts and tables are in the report.

01

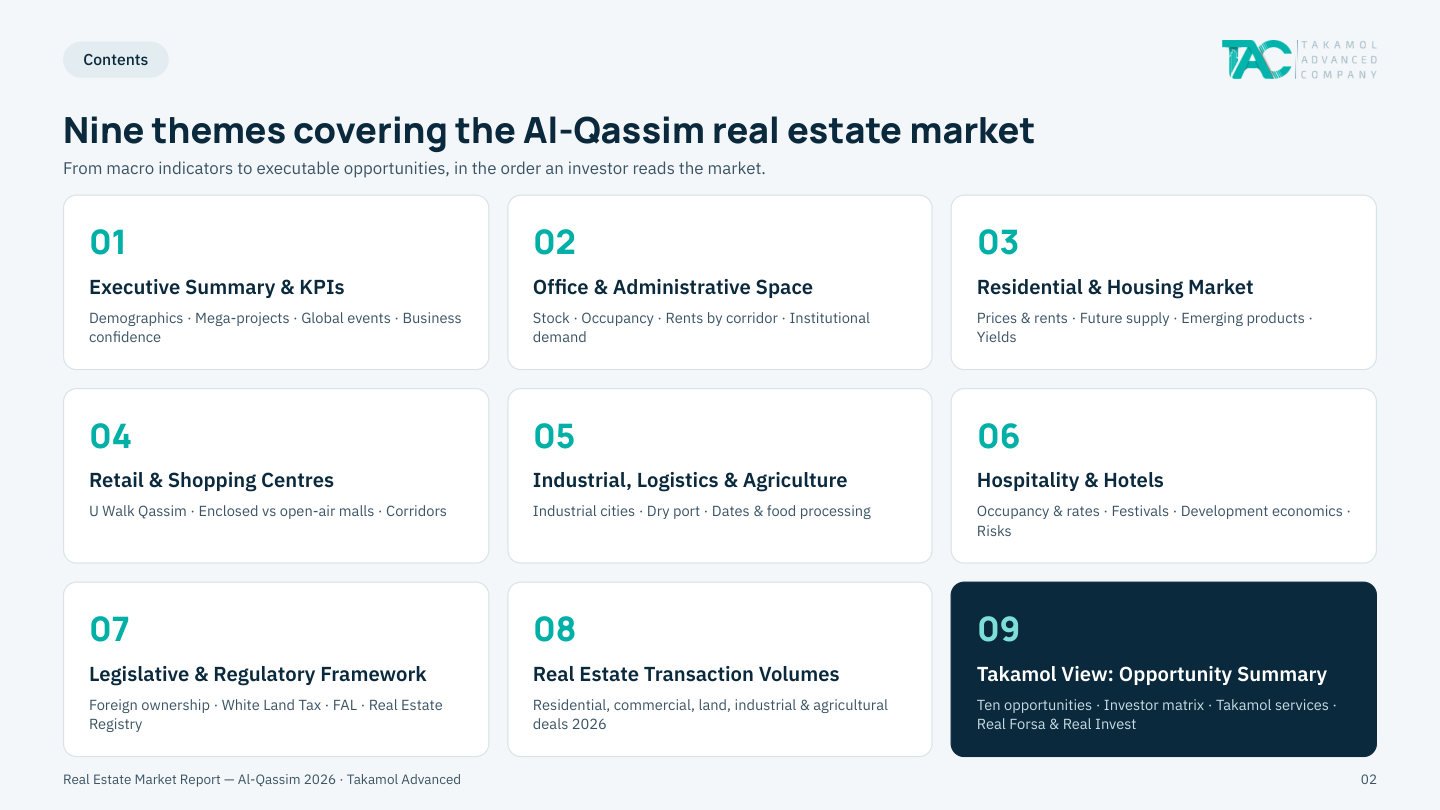
Executive Summary & KPIs

Al-Qassim has a population of 1.34 million, growing 2.31% a year, with average household income of SAR 15,470 a month. The report estimates annual need at 4,000–5,000 new homes against roughly 2,800 planned deliveries a year in 2026–2028, an estimated annual shortfall of 1,200–2,200 units. It also records 47 investment opportunities offered in Buraidah in Q1 2026 and places logistics and cold storage at the top of its risk-return matrix, with net yields of 8.5–9.2%.
02

Office & Administrative Space

Al-Qassim's office market is local and specialised, driven by large family businesses and the head offices of food and healthcare companies, with a clear preference for modern buildings: 97% occupancy against 75% for traditional offices. Modern space on Buraidah's main corridors rents for SAR 400–620 per m² a year, compared with SAR 300–420 in Unaizah, and commercial lease transactions are growing 11.1% a year. Energy, industry and healthcare account for 45% of institutional demand, ahead of the roughly 1 million m² Tijan mixed-use scheme due in 2027–2028.

03

Residential & Housing Market

The housing stock stands at 345,000 occupied units, with sale prices of SAR 1,900–2,850 per m² for apartments and SAR 2,300–3,600 per m² for villas, up 1.2% and 1.6% year on year respectively. Some 8,500 units are due for delivery in 2026–2028, 42% of them from NHC and Sakani, with more than 12,600 further units in planning for 2028–2030. North Buraidah leads on price at SAR 3,200–4,600 per m² for villas, while modern apartments for professionals near the health cluster and university offer estimated net yields of 7.5–9.0%.

04

Retail & Shopping Centres

Retail is shifting to modern destinations that blend shopping, dining and entertainment, led by U Walk Qassim (60,000 m² GLA, more than 135 stores, due Q4 2026) and the new Unaizah mall (about SAR 85 million), which together add more than 125,000 m² of modern GLA by 2028. Open-air centres outperform, with 88–94% occupancy and rents of SAR 850–1,600 per m² a year, against 82–89% for enclosed malls, and rents up to 20% higher at the top end. The northern corridor leads, at SAR 1,100–1,600 per m² and 92% occupancy.

05

Industrial, Logistics & Agriculture

Industry and logistics is Al-Qassim's highest-occupancy, highest-yield segment. The region has 730 producing factories and SAR 30.9 billion in industrial investment, and Buraidah's First Industrial City runs at 96% occupancy against a 77% average for industrial cities. Modern warehouses rent for about SAR 220 per m² versus about SAR 120 for traditional stock, with target net yields of 8.5–9.2%. Demand is fed by more than 10.87 million palm trees, over 584,000 tonnes of dates a year, the dry port and the 1,800 MW Qassim 1 solar project.

06

Hospitality & Hotels

The market has about 6,150 licensed hotel keys, with annual occupancy of 54.2% and an average daily rate of SAR 365. Occupancy rises to 85–92% at festival peaks, a gap of about 40 points between the August dates carnival and the quiet months, and business travel makes up 41% of demand. The report sees serviced apartments as the best fit for Al-Qassim, with an expected IRR of 16.5–19.0% and a 5.2–6.5-year payback, while Tourism Development Fund packages can cover up to 60% of capital costs for eligible projects.

07

Legislative & Regulatory Framework

Reforms in 2025–2026 reshaped the market, notably 100% ownership for non-Saudis in approved investment and industrial zones in Buraidah and Unaizah, and a white-land fee of 2.5% of land value a year, phased in over three stages, which has brought about 15 million m² into development or ownership transfer. Transaction costs total about 7.5% (5% transaction tax plus brokerage capped at 2.5%), first homes are tax-exempt up to SAR 1,000,000, and the real estate registry covers 22,937 parcels in 28 neighbourhoods of Buraidah and Unaizah.

08

Real Estate Transaction Volumes

The residential sector recorded 14,282 transactions worth SAR 5.03 billion in 2026, about 7% of the Kingdom's total, at an average of SAR 352,000 per deal, less than a third of the Riyadh average. Commercial activity was smaller: 153 deals worth SAR 157.3 million, averaging SAR 1.03 million each. The residential price per m² in recorded deals ranges from SAR 667 in Buraidah to SAR 108 in Al Badai, and 21.36 million m² of vacant land was traded.

09

Takamol View: Opportunity Summary

The report ranks ten investment opportunities by strength. At the top are Grade A warehouses and cold storage near the First Industrial City and the dry port, at net yields of 8.5–9.2%, followed by serviced apartments for health and academic staff in Buraidah (IRR of 16.5–19%) and modern apartments near the university and health cluster (yields of 7.5–9%). An investor matrix matches each opportunity to capital and time horizon, from individuals with SAR 0.3–2 million targeting 6.0–9.0% to institutions with more than SAR 200 million targeting 7.5–9.5%.

The report's contents page

Get the full report

The full report includes the detailed analysis, charts, data tables and their sources, along with the investment opportunity maps.

Download the PDF reportPDF · 66 pages · 15.9 MB

This summary is drawn from Takamol Advanced's 2026 real-estate market reports, and its figures are for general information. See the full report for detail and sources.

More reports