Home›Knowledge Center›Jeddah

Real Estate Market Report — Jeddah Region 2026
Real Estate Market Reports · 2026 Edition

Real Estate Market Report — Jeddah Region 2026

Strategic analysis and market dynamics for 2026

This Takamol Advanced report offers an institutional reading of the Jeddah Governorate property market in 2026, covering offices, residential, retail, logistics and hospitality alongside the regulatory framework, transaction data and opportunity maps. It draws on Real Estate Registry and other official data for January to August 2026, analysed across the city's four zones for investors, developers and decision-makers.

PDF · 67 pages · 14.5 MB

Key figures

3.75 million

Residents of Jeddah Governorate

95%

Grade A office occupancy

97%

Average logistics occupancy in Jeddah

7,000–13,000 units

Estimated annual housing shortfall

SAR 16.87 billion

Residential deals, January to August 2026

600,000+ sq m

New retail space planned by 2030

What the report covers

A summary of each theme. The full detail, charts and tables are in the report.

01

Executive Summary and KPIs

The summary presents Jeddah as the Kingdom's commercial and logistics gateway on the Red Sea, home to 3.75 million people, 69% of them under 35. The market runs near capacity: 95% occupancy for Grade A offices, 97% for warehouses and 96% for strip centres, against 64.5% a year for hotels. Planned housing supply of about 15,000 units a year meets only part of an estimated annual need of 22,000–28,000, while giga-projects from Marafy and Jeddah Central to an airport expanded to 100–114 million passengers mark the milestones repricing the market through 2034.
02

Office and Workspace Sector

Office stock exceeds 2.8 million sq m, about 55% of Riyadh's, yet Grade A vacancy is no more than 5.1% and occupancy 93–95%: a shortage of quality space, not a glut. Grade A rents are growing 7–10% a year with net yields of 7–8%, led by King Abdulaziz Road at SAR 1,250 per sq m a year versus SAR 550 on King Fahd Road. The report sets out an entry window ahead of a 303,000 sq m supply wave in 2028–2030, 200,000 sq m of it in KAIA City.

03

Residential and Housing Market

Housing stock exceeds 1.24 million units, more than 62% of them apartments. Apartment prices average SAR 3,900–4,800 per sq m, up 4.0%, and apartment rents rose 6.3%. Some 45,000 units are scheduled for delivery in 2026–2028, with another 67,500 in planning for 2028–2030, against an annual need of 22,000–28,000 units. Prices across Jeddah's four zones differ by up to roughly a factor of two, and small investment apartments near the Corniche and the rail station achieve net yields of up to 8.5%.

04

Retail and Shopping Centres

Existing leasable area exceeds 2.78 million sq m. Major destinations are 94.5% occupied and open-air centres 96%, compared with 89% for traditional regional malls, while restaurants, entertainment and open-air frontages draw 52% of daily footfall. The open-air model commands a rent premium of up to 40% at the top of the range. More than 600,000 sq m of new space is planned by 2030, about 22% on top of current stock, concentrated in open-air and waterfront destinations and led by Westfield Jeddah at over 155,000 sq m.

05

Warehousing and Logistics

Logistics is Jeddah's highest-occupancy, highest-yield sector, with 97% occupancy and an estimated net yield of 8.5–10.0% across about 20.2 million sq m. Supply grows only about 1.4% a year while rents rise by roughly 8%. Prime sites in the port–Khumrah–airport triangle reach SAR 387 per sq m a year, against SAR 160 for traditional warehouses. Demand is fed by Jeddah Islamic Port's handling capacity of 130 million tonnes, the special logistics zones, e-commerce and a clear shortfall in cold-storage capacity.

06

Hospitality and Hotels

The market has 16,800–17,200 hotel rooms with 64.5% annual occupancy, rising to 88–94% during Ramadan, school holidays and the Formula 1 season, an average daily rate of SAR 735 and RevPAR of SAR 474. Leisure and beach seasons account for 40% of demand and Haramain-related travel for 32%. Serviced apartments stand out as the fastest to pay back, with an expected IRR of 13.5–16.0% and a 6.2–7.5-year payback, while Tourism Development Fund financing can cover up to 50% of capital costs.

07

Legislative and Regulatory Framework

The report tracks sweeping regulatory decisions between Q3 2025 and Q1 2026 that shifted the market from speculation to operational sustainability: the non-Saudi ownership law, updated Wafi off-plan rules, wider white land fees (2.5% a year, rising to as much as 10%), and the Tawazoun platform capping residential land for eligible citizens at SAR 1,500 per sq m. Lying outside the Haramain zone, Jeddah is the natural gateway for foreign ownership in the Western Region. Transaction tax stands at 5%, with first homes exempt up to SAR 1,000,000.

08

Real Estate Transaction Volumes

Real Estate Registry data for January to August 2026 show 14,391 transactions in Jeddah Governorate. Residential accounted for 95.6% of them: 13,753 deals worth SAR 16.87 billion, averaging SAR 1.23 million per deal and SAR 2,382 per sq m. Commercial recorded 635 deals worth SAR 5.94 billion, averaging SAR 9.35 million, or 7.6 times the residential average, while agriculture saw just 3 deals. A benchmark against Riyadh puts Jeddah's Grade A office rents roughly 40–45% lower.

09

Takamol View: Opportunity Summary

The report closes with ten investment opportunities ranked by strength, led by Grade A warehouses in the port–Khumrah–airport triangle (97% occupancy, 8.5–10% net yield), followed by serviced apartments near the airport and the Haramain railway with an IRR of 13.5–16%, and open-air lifestyle centres in the northern districts. An investor matrix then matches opportunities to four profiles, from individuals with SAR 0.5–3 million in capital to institutions and funds with more than SAR 300 million.

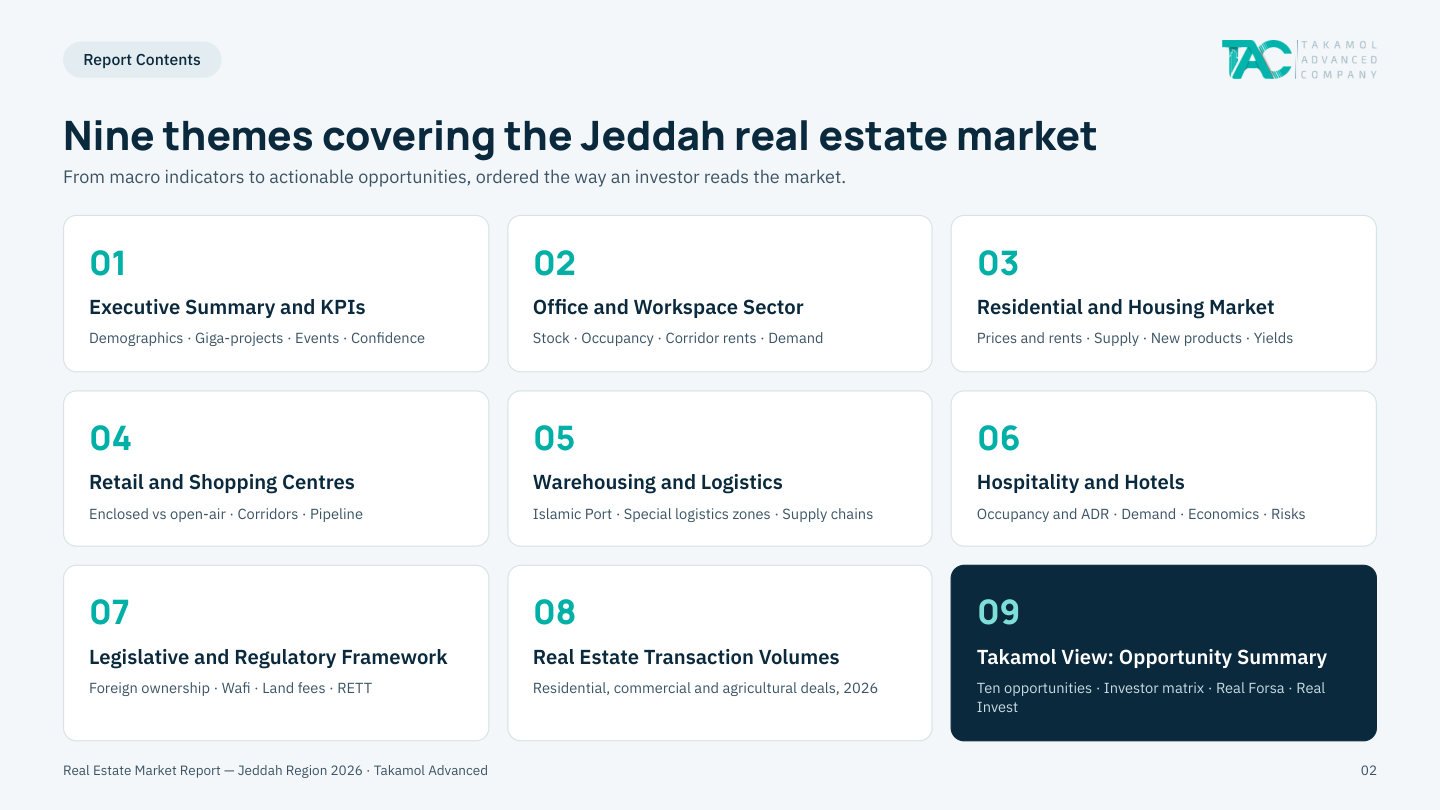
The report's contents page

Get the full report

The full report includes the detailed analysis, charts, data tables and their sources, along with the investment opportunity maps.

Download the PDF reportPDF · 67 pages · 14.5 MB

This summary is drawn from Takamol Advanced's 2026 real-estate market reports, and its figures are for general information. See the full report for detail and sources.

More reports