Home›Knowledge Center›Dammam

Real Estate Market Report — Dammam 2026
Real Estate Market Reports · 2026 Edition

Real Estate Market Report — Dammam 2026

Strategic analysis and market dynamics for 2026

This Takamol Advanced report offers an institutional reading of the real estate market in the Dammam metropolitan area (Dammam, Khobar and Dhahran), extending to Qatif and Ras Tanura, across the office, residential, retail, logistics and industrial, and hospitality sectors. It draws on Real Estate Registry transactions and field surveys for January to August 2026, compared with the same period of 2025, and links the figures to the regulatory framework, transaction data and opportunity maps for investors, developers and decision-makers.

PDF · 66 pages · 14.7 MB

Key figures

2.3 million

Residents of the Dammam metro area

34

Global firms licensed for regional headquarters

8.1 million m²

Logistics stock in the Dammam metro

8.5–9.5%

Target net yield on logistics assets

SAR 5.4 billion

Value of residential deals in Dammam

98%

Occupancy of open-air retail centres

What the report covers

A summary of each theme. The full detail, charts and tables are in the report.

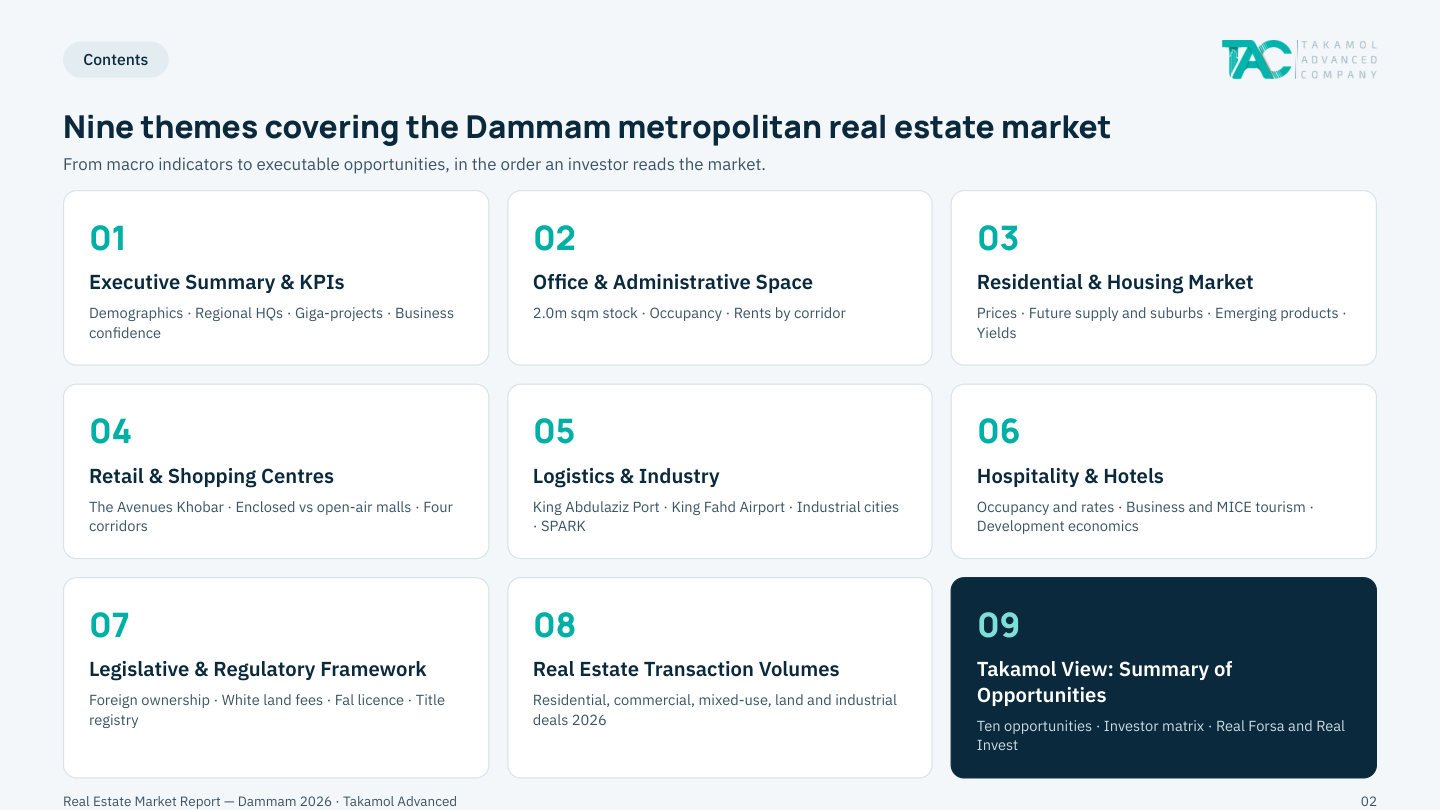
01

Executive Summary & KPIs

The report positions Dammam as the Kingdom's industrial and logistics centre of gravity, with a metro population of 2.3 million, annual growth of about 2.8% and average household income of SAR 15,000 a month. The Eastern Province holds 5,456 active foreign investment licences, and 34 global companies have regional headquarters licences there. Annual housing need is estimated at 9,000–11,000 units against planned deliveries of roughly 6,000–6,700 a year, and a 2026–2034 roadmap runs up to Aramco Stadium hosting World Cup 2034 matches, alongside a risk–return matrix for each sector.
02

Office & Administrative Space

Office stock in the Dammam metro stands at about 2.0 million m², with Grade A occupancy of 78.6% according to JLL versus around 91% for high-quality assets in CBRE's estimate. Grade A rents reached about SAR 994/m² a year, up 9.2%+, and King Fahd Road leads the corridors at SAR 1,100/m². With roughly 130,000 m² of new space due by end-2026 and net absorption of 40,000–60,000 m² a year, the report expects rents to grow by 2%+ to 5%+ a year through 2028.

03

Residential & Housing Market

The existing housing stock is about 736,000 units, with average sale prices of SAR 3,578/m² for apartments and SAR 4,917/m² for villas, showing only slight annual growth. Villas and duplexes made up 67.1% of purchase deals in Q1 2026, and 18,000–20,000 units are planned for delivery in 2026–2028, about 56% of them from National Housing Company (NHC) communities in west and central Dammam. The report compares prices across four geographic bands and models three investment cases with gross yields of 5.8% to 7.8%.

04

Retail & Shopping Centres

Existing retail leasable area is about 1.42 million m² and is expected to reach around 2.0 million m² by 2028, driven by projects such as The Avenues Khobar (about 175,000 m² in phase one) and Othaim Park Dammam. Major destinations run at about 94% occupancy, open-air centres at 98% versus 92% for enclosed regional malls, and open formats command a rent premium of up to 65%+. The report targets net rental yields of 7.0–8.0% and compares rents and occupancy across four commercial corridors.

05

Logistics & Industry

The report identifies logistics as Dammam's highest-yielding sector, with stock above 8.1 million m², a target net yield of 8.5–9.5% and occupancy of about 93% in serviced logistics zones. Modern Grade A warehouses rent for about SAR 260/m², against roughly SAR 140/m² for conventional stock. It traces the supply chain from King Abdulaziz Port and King Fahd International Airport (targeting 19.3 million passengers by 2030) to the industrial cities and SPARK, and highlights build-to-suit warehouses and small multi-tenant logistics parks.

06

Hospitality & Hotels

The Dammam metro has about 17,500 hotel keys, with annual occupancy of 55.8% rising to 80–88% during exhibition and holiday peaks, an average daily rate of SAR 447 (+5.8%) and RevPAR of SAR 249 (+8.2%). Demand comes from energy-sector business travel and Gulf visitors crossing the King Fahd Causeway. Comparing three development categories, the report finds serviced apartments offer the highest expected IRR (15.0–17.5%) and the fastest payback (5.8–7.0 years), with Tourism Development Fund financing covering up to 60% of costs.

07

Legislative & Regulatory Framework

The report reviews the 2025–2026 regulatory changes that reshaped the market: the non-Saudi ownership law, with 100% ownership in SPARK, Ras Al-Khair and the Dammam and Khobar waterfronts, and the three-phase white land tax of up to 10% a year, with more than 85 million m² invoiced in the Dammam metro. It also covers the 5% real estate transaction tax, the first-home exemption up to SAR 1,000,000, the new real estate contributions system, the FAL licence with a 2.5% brokerage commission cap, and real estate registration.

08

Real Estate Transaction Volumes

Drawing on 2026 Real Estate Registry data, the report breaks down deals by sector. The residential segment recorded 4,450 transactions worth SAR 5.4 billion, averaging SAR 1.226 million each, with Al Shula district alone accounting for 2,100 deals (47% of transactions and 56% of value). Commercial deals numbered 280–380, worth SAR 1.1–1.4 billion; 165 vacant-land deals absorbed SAR 2.87 billion at an average of SAR 17.37 million; and the industrial segment logged about 85 deals worth nearly SAR 210 million.

09

Takamol View: Summary of Opportunities

The report closes with ten investment opportunities ranked by strength, led by Grade A warehouses near King Abdulaziz Port and the First Industrial City at a net yield of 8.5–9.5%, followed by serviced apartments for professionals with an IRR of 15–17.5%, and open-air lifestyle centres on the Corniche and in Khobar at 98% occupancy. An investor matrix then matches each opportunity to investor type, from individuals with SAR 0.4–2 million of capital and a target yield of 5.5–8.0% to institutions and funds deploying more than SAR 250 million.

The report's contents page

Get the full report

The full report includes the detailed analysis, charts, data tables and their sources, along with the investment opportunity maps.

Download the PDF reportPDF · 66 pages · 14.7 MB

This summary is drawn from Takamol Advanced's 2026 real-estate market reports, and its figures are for general information. See the full report for detail and sources.

More reports