Home›Knowledge Center›Madinah

Real Estate Market Report — Madinah 2026
Real Estate Market Reports · 2026 Edition

Real Estate Market Report — Madinah 2026

Strategic analysis and market dynamics for 2026

This report offers an institutional reading of Madinah's office, residential, retail, knowledge-economy and hospitality sectors, together with the regulatory framework, transaction data and opportunity maps, for investors, developers and decision-makers. It covers the city of Madinah and its urban area over the reference period January to August 2026, with analysis at the level of zone, corridor and district.

PDF · 66 pages · 13.5 MB

Key figures

21 million

visitors to the Madinah region in 2025

SAR 9.69 billion

value of 12,336 property deals in 2026

+49%

annual growth in residential deal value

74.7%

average annual hotel occupancy in 2026

98,500 units

estimated additional housing need by 2030

47,000 rooms

planned in Rua Al Madinah by 2030

What the report covers

A summary of each theme. The full detail, charts and tables are in the report.

01

Executive Summary & Key Indicators

The Madinah region has 2.14 million residents growing 4.1% a year, and it welcomed 21 million visitors in 2025, with tourism spending above SAR 52 billion. The stock of foreign direct investment reached SAR 60.4 billion by the end of 2024, and 213 development projects worth more than SAR 210 billion are under way. The report puts additional housing need at about 98,500 units by 2030 against planned deliveries of roughly 6,900 units a year, and maps return against risk for every sector.
02

Office & Commercial Space

Madinah's office market is still emerging and is led by the Knowledge Economic City, with modern offices averaging about SAR 850/m² a year on leases of 3 to 5 years. Grade A space runs at roughly 98% occupancy, against about 75% for traditional offices. King Abdulaziz Road and Knowledge City command the top Grade A rents at SAR 1,000/m² with 6% annual growth, versus SAR 750 on Al Hijrah Road and secondary corridors, leaving an entry window before Multaqa Al Madinah 2 and Knowledge Gardens deliver in 2027–2028.

03

Residential & Housing Market

The existing housing stock stands at 458,800 units and is expected to reach 549,200 units by 2030. Average apartment prices rose 2.5% to SAR 3,835/m², while villa prices eased 0.5% to SAR 3,500/m², and apartments accounted for 58% of deals. Apartment prices range from SAR 7,500–13,500/m² in the central area to 2,700–3,500 in the new suburbs, and the report compares three investment models with gross yields of 6.0% to 9.5%.

04

Retail & Shopping Centres

Madinah has more than 260,000 m² of leasable area in its main operating and near-complete centres, where the leading malls run at 94–97% occupancy with rents of SAR 1,600–2,000+/m² a year. Open-air centres outperform with 98% occupancy and rents of SAR 3,500–4,500/m² for premium frontages near the Haram and visitor routes. With more than 150,000 m² of modern leasable space planned in Knowledge City by 2028, King Abdulaziz Road is becoming the city's new retail centre of gravity.

05

Knowledge Economy, Industry & Logistics

The Madinah region holds 25 million m² of industrial land, and its industrial city hosts 155 producing factories with 82% occupancy of allocable industrial land, pointing to a need for further expansion. The Knowledge Economic City adds 1.18 million m² of major project space, while airport capacity rises to 18 million passengers by the end of 2027. The report highlights cold storage and central catering facilities serving 661 hospitality establishments, with target yields of 7.5–8.5%.

06

Hospitality & Hotels

Existing hotel supply is estimated at 28,500–42,000 keys, with annual occupancy of 74.7% that climbs to around 100% during Ramadan and Hajj. The average daily rate reached SAR 538 (+8.5%) and RevPAR SAR 402 (+12.4%). Serviced apartments deliver the highest IRR (16.0–18.5%) and the shortest payback (5.2–6.5 years) compared with five-star hotels, while the Tourism Development Fund covers up to 60% of capital costs for eligible projects.

07

Legal & Regulatory Framework

This section covers the new ownership rules, which open full 100% ownership zones in Knowledge City, Rua Al Madinah, Dar Al Hijrah and investment corridors outside the Haram boundary, with direct ownership limited to citizens and non-Saudi Muslims. Transaction costs total about 7.5% (a 5% transaction tax plus brokerage capped at 2.5%). The 2.5% annual white-land fee has brought more than 32 million m² under billing, moved 8.5 million m² into development and cut land costs for developers by 10–15%.

08

Real Estate Transaction Volumes

The market recorded 12,336 property transactions worth SAR 9.69 billion in 2026. Residential trading reached SAR 3.4 billion, up 49% in value and 38% in deal count, led by Al Rumanah district with 627 deals worth SAR 594 million. The commercial segment logged 754 deals worth SAR 1.59 billion at an average of SAR 2.11 million per deal, while 149 agricultural deals totalled SAR 489.3 million.

09

Takamol View: Opportunity Summary

The report closes with ten investment opportunities ranked by strength, led by serviced hotel apartments on King Abdulaziz and Al Hijrah roads with a 16–18.5% IRR, followed by upper-midscale hotels in Knowledge City and Quba Avenue, then dual-key apartments yielding 8–11%. An investor matrix matches each opportunity to an investor profile, from individuals with SAR 0.5–2 million in capital to institutions and funds deploying more than SAR 300 million.

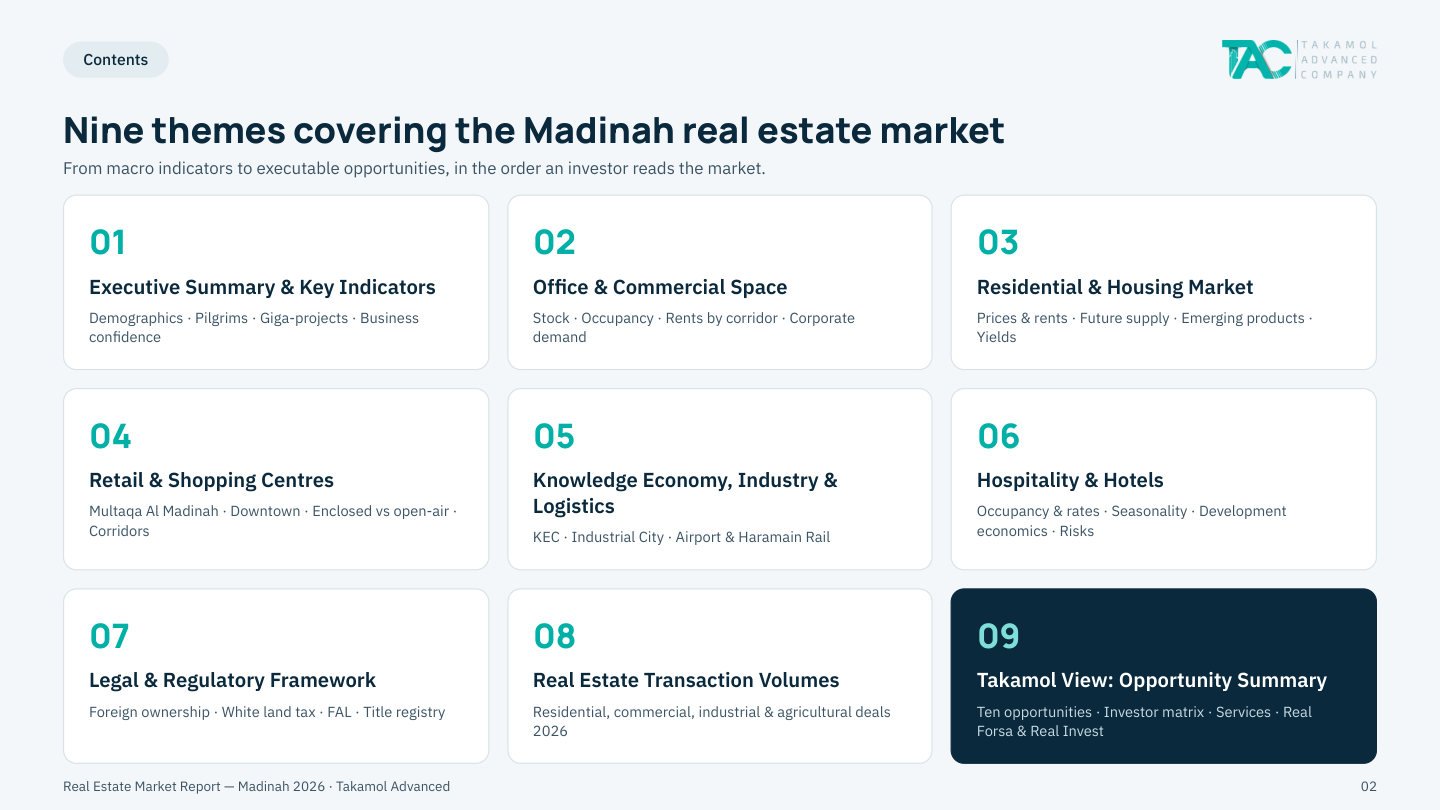
The report's contents page

Get the full report

The full report includes the detailed analysis, charts, data tables and their sources, along with the investment opportunity maps.

Download the PDF reportPDF · 66 pages · 13.5 MB

This summary is drawn from Takamol Advanced's 2026 real-estate market reports, and its figures are for general information. See the full report for detail and sources.

More reports